Approved for More, Better Off With Less: The Case for Borrowing Below Your Maximum
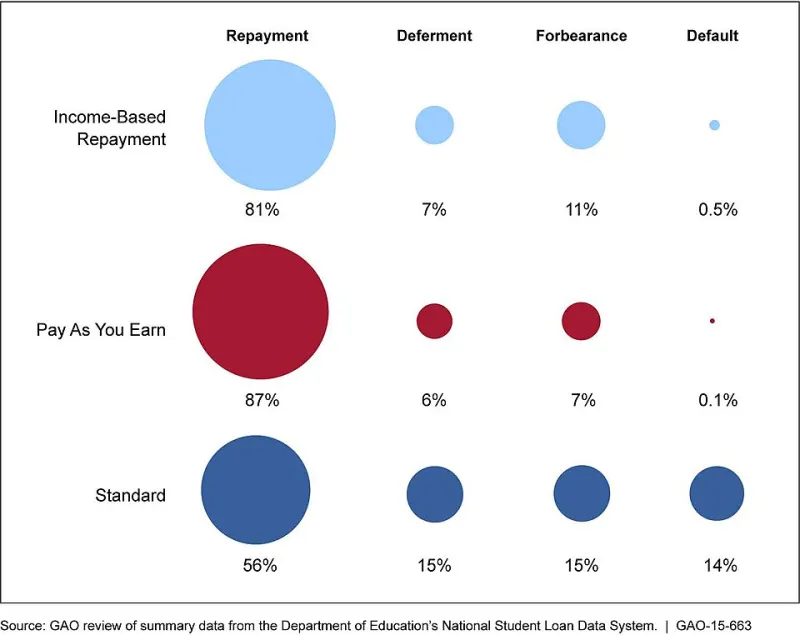
Photo: U.S. Government Accountability Office from Washington, DC, United States, Public domain, via Wikimedia Commons
There is a particular kind of satisfaction that comes with a strong loan approval. The lender has reviewed your credit profile, assessed your income, and determined you qualify for a substantial amount. It can feel like a reward — validation that your financial habits have earned you access to meaningful capital.
But here is the question that most borrowers never stop to ask: just because a lender is willing to extend $25,000, does that mean you should take all of it?
At AmeriLoanSearch, we help consumers compare loan offers across multiple lenders to find the most competitive terms available. And one pattern we consistently observe is that the borrowers who fare best over time are often the ones who borrow with restraint — not recklessness.
What Maximum Approval Actually Means
When a lender determines your maximum loan eligibility, they are calculating the upper boundary of what they believe you can repay based on your income, credit score, existing debt obligations, and other underwriting criteria. That number reflects their risk threshold, not a recommendation for what you should borrow.
Lenders are in the business of extending credit and collecting interest. A higher loan amount generally means more revenue for them over the life of the loan. The approval ceiling, in other words, is designed to protect the lender — not necessarily to optimize your financial outcome.
Understanding this distinction is the first step toward making a more deliberate borrowing decision.
The Interest Math Nobody Wants to Do
Consider a straightforward example. Suppose you are approved for $20,000 at a 12% APR over 48 months, but your actual need is closer to $14,000.
Borrowing the full $20,000 would result in a monthly payment of approximately $527 and total interest paid of roughly $5,280 over the loan term. Borrowing only $14,000 under the same terms drops your monthly payment to around $369 and reduces your total interest cost to approximately $3,696 — a savings of nearly $1,600.
That is not a trivial difference. And when you factor in the possibility of a shorter repayment term on a smaller balance, the savings can compound further. Borrowed less, paid less interest, freed up monthly cash flow — all without sacrificing the financial goal that prompted the loan in the first place.
How Lenders View Your Debt Load Going Forward
Your loan approval is not the end of your credit story. Every new debt obligation you take on is reported to the credit bureaus and becomes part of your credit profile. Future lenders — whether for a mortgage, auto loan, or another personal loan — will evaluate your debt-to-income ratio (DTI) when you apply.
DTI is calculated by dividing your total monthly debt obligations by your gross monthly income. A borrower carrying a $527 monthly payment on a personal loan starts future credit applications in a materially weaker position than one carrying a $369 payment — even if both were approved for the same maximum amount.
Borrowing conservatively today preserves your borrowing capacity for tomorrow. That flexibility has real value, particularly if an unexpected expense or financial opportunity arises in the next few years.
The Psychology of the Approval Ceiling
There is a well-documented behavioral tendency in personal finance: people tend to expand their spending to match their available resources. Psychologists sometimes call this "lifestyle creep," but it applies equally to borrowing behavior.
When a borrower receives a $20,000 approval, the original $14,000 need can quietly expand. The kitchen renovation gets a few upgrades. The vacation budget stretches. The buffer "just in case" grows larger. Before long, the full approved amount has been drawn down — not because the need was there, but because the access was.
Building discipline into your borrowing decision from the outset is a practical defense against this tendency. Determine what you genuinely need before you apply, and treat that figure as your target — not the lender's ceiling.
Scenarios Where Borrowing Less Pays Off
Not every situation calls for the same approach, but there are several common scenarios where requesting a smaller loan than your maximum approval is clearly the smarter move.
Home improvement projects with variable costs. If you are renovating a bathroom and have a rough estimate of $10,000, borrowing $15,000 "just in case" locks you into interest charges on money you may never spend. A better approach is to borrow closer to your realistic estimate and revisit financing if costs genuinely exceed projections.
Debt consolidation with a clear payoff number. When consolidating credit card balances, the goal is to pay off specific, known amounts. Borrowing beyond that total defeats the purpose of the exercise and introduces new debt without a corresponding reduction in existing obligations.
Borrowers approaching a major financial milestone. If you anticipate applying for a mortgage within the next 12 to 24 months, keeping your personal loan balance — and monthly payment obligation — as low as possible can meaningfully improve your DTI when that application is reviewed.
Borrowers with variable or uncertain income. For gig workers, freelancers, or anyone whose earnings fluctuate seasonally, a smaller monthly payment provides a more sustainable commitment during slower periods. The margin between what you owe and what you earn is your financial cushion.
What to Ask Before You Finalize Your Loan Amount
Before accepting any loan offer, it is worth working through a short set of practical questions.
First, what is the specific expense or purpose this loan is meant to address? Assign a number to it — not a range, but a concrete figure based on actual quotes or known costs.
Second, what monthly payment can you absorb without meaningfully constraining your other financial priorities? Run your household budget with the proposed payment included and assess whether the margin is comfortable.
Third, are there alternative sources for any portion of this need? Savings, a 0% APR credit card for a short-term purchase, or a smaller supplemental loan in the future may cover gaps without requiring you to over-borrow now.
Finally, how does this loan fit into your broader credit picture over the next two to three years? If you have goals that will require additional financing, consider how today's decision affects tomorrow's options.
Comparing Offers with the Right Loan Amount in Mind
When you use a loan comparison platform like AmeriLoanSearch, you have the ability to search for offers based on the amount you actually need — not the maximum you might qualify for. This approach allows you to evaluate APRs, origination fees, and repayment terms on a more relevant and accurate basis.
A lender offering a competitive rate on a $15,000 loan may present different terms on a $25,000 request. Anchoring your comparison to your true borrowing target produces results that are more actionable and more aligned with your actual financial situation.
The Discipline Dividend
Borrowing less than you are approved for is not a sign of financial timidity. It is a deliberate choice to prioritize long-term stability over short-term access. It reduces the total cost of the loan, preserves your debt capacity for future needs, and keeps your monthly obligations manageable.
The approval ceiling a lender sets is a ceiling — not a target. The smartest borrowers treat it that way.