Slow Paperwork, Higher Rates: What Your Loan Application Timeline Reveals to Lenders
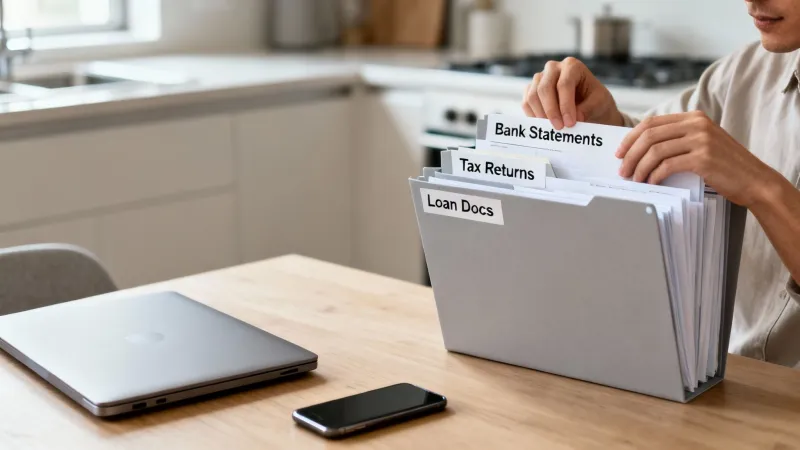
Photo: person organizing financial documents at desk for loan application, via cdn.outrank.so
When most Americans sit down to apply for a personal loan, their attention gravitates toward the obvious variables: credit score, debt-to-income ratio, employment status. These are the metrics that dominate personal finance conversations, and for good reason—they matter enormously. What rarely enters the conversation, however, is something far more controllable: the pace and completeness of the application itself.
Lenders do not evaluate borrowers purely through static financial snapshots. They also observe behavior. And the behavior of a borrower during the application process—how quickly documents are submitted, how thoroughly forms are completed, how promptly follow-up requests are addressed—sends its own set of signals. Those signals carry weight, and in some cases, they carry a price.
The Underwriting Clock Starts Before You Realize It
The moment a borrower submits an initial loan application, a process begins on the lender's side that is far more dynamic than most people appreciate. Underwriters and automated loan systems begin building a risk profile almost immediately. Part of that profile is constructed from the documents and information you provide. Another part, however, is constructed from the timing of what you provide.
Most lenders operate on internal processing windows. A complete, well-organized application that arrives with all supporting documentation intact moves through the pipeline efficiently. An application that trickles in piecemeal—where pay stubs arrive days after the initial submission, where bank statements must be requested twice, where identity verification takes a week to resolve—does not simply sit idle. It ages. And an aging application can age out of its initial rate tier.
This happens for a straightforward reason: loan pricing is not always static. Interest rate offers are often tied to the market conditions and the lender's internal risk appetite at the moment the application is assessed. A delay of several days or weeks can push a file into a reassessment window, where rates may have shifted or where the underwriter applies greater scrutiny simply because the file has lingered.
Incomplete Submissions as Inadvertent Risk Signals
Beyond timing, the completeness of a loan application carries its own interpretive weight. When a borrower submits an application with gaps—missing income documentation, an unsigned form, a mismatch between stated and verified employment—underwriters must make a judgment call. In many cases, the charitable interpretation prevails. But lenders are in the business of managing risk, and a pattern of incomplete information, however innocent, can shift a borrower's perceived risk profile.
Consider how lenders view a borrower who cannot promptly produce two years of tax returns, or who provides bank statements that are inconsistent with the income figures stated on the application. Even if there is a perfectly reasonable explanation—self-employment income that fluctuates, a recent job change, a clerical error—the absence of clean, consistent documentation introduces uncertainty. And uncertainty, in lending, is priced.
This does not mean that borrowers with complex financial situations are automatically penalized. It does mean that those borrowers have a heightened responsibility to anticipate documentation gaps and address them proactively, rather than leaving underwriters to draw their own conclusions.
The Documents That Commonly Derail Timelines
Certain categories of documentation are disproportionately responsible for application delays. Awareness of these common sticking points allows borrowers to prepare in advance rather than scrambling reactively.
Proof of income is the most frequent source of delay. Salaried employees may assume that recent pay stubs are sufficient, but many lenders require two to three months of documentation, and some request W-2 forms for the prior two tax years. Self-employed borrowers face an even higher bar, often needing to provide complete federal tax returns, profit-and-loss statements, and sometimes a letter from a CPA.
Bank statements present a similar challenge. Lenders typically request two to three months of statements from all active accounts. Borrowers who use multiple financial institutions, or who have recently moved funds between accounts, may find that their statements raise questions that require additional explanation.
Identity verification has become increasingly rigorous in the post-pandemic lending environment. Government-issued identification, Social Security verification, and in some cases, video or biometric confirmation may be required. Delays in any of these steps can hold an entire application in suspension.
Employment verification can also introduce unexpected friction, particularly when borrowers have recently changed jobs, hold multiple positions, or work for smaller employers whose HR departments are slow to respond to third-party verification requests.
How to Approach Your Application Like a Prepared Borrower
The practical implication of all of this is that loan applications reward preparation in a very direct, financial sense. Borrowers who treat the application process as a documentation sprint—assembling everything before initiating the process rather than after—tend to move through underwriting faster, encounter fewer follow-up requests, and present a more coherent picture of their financial reliability.
A useful starting point is to build what might be called an application packet before submitting anything. This packet should include the following:
- Two to three months of pay stubs (or equivalent income documentation for non-traditional earners)
- Two years of federal tax returns, including all schedules
- Two to three months of bank statements from all primary accounts
- A current government-issued photo ID
- Proof of residence, such as a utility bill or lease agreement
- Any documentation relevant to existing debts, including current balances and monthly payment obligations
Having these materials prepared in advance accomplishes two things. First, it eliminates the reactive scramble that causes most application delays. Second, it demonstrates to the lender—through behavior, not just data—that the borrower is organized, financially aware, and serious about the process.
The Comparison Shopping Dimension
For borrowers who are comparing multiple loan offers across lenders—which is, generally speaking, the most effective way to secure a competitive rate—the timeline dimension becomes even more consequential. Rate locks and pre-qualification windows are finite. Submitting a complete application to Lender A while Lender B is still waiting on your income documentation means that your comparison is being conducted on an uneven playing field. By the time Lender B finalizes its offer, Lender A's terms may have shifted.
The most effective approach is to prepare all documentation before initiating applications with any lender, then submit complete packets to multiple lenders within a narrow window. This approach not only keeps the comparison process synchronized—it also concentrates credit inquiries within a short timeframe, which limits the impact on your credit score under most scoring models.
Thoroughness Is a Financial Strategy
The loan application process is not merely an administrative hurdle. It is, in a meaningful sense, an extension of the financial narrative you are presenting to a lender. A complete, promptly submitted, well-organized application tells a story of reliability and preparedness. An application that arrives in fragments, requires repeated follow-up, and takes weeks to close tells a different story—one that lenders may price accordingly.
At AmeriLoanSearch, we encourage borrowers to approach the application process with the same rigor they bring to evaluating loan terms. The rate you ultimately receive reflects not only who you are on paper, but how you behave in the process of proving it. Taking the time to prepare thoroughly, before the clock starts, is one of the most straightforward ways to protect the rate you have worked to earn.